Tech
Thought Leadership
Oct 8, 2026
4 minutes


Choosing a loan administrator for private credit starts with one question: can you trust the numbers enough to run your business on them?
If your team still maintains parallel books, rebuilds calculations, or waits days for answers to basic questions, you are carrying much of the work you outsourced. The goal of outsourced loan administration is to hand off the work, not the visibility.
That trust depends on being able to see and understand the work. Your loan data should remain yours, accessible from day one. You should be able to inspect a balance, trace a calculation to its inputs, and investigate a discrepancy the moment it arises.
The administrator's technology makes this possible at scale. It is also the foundation for automation and AI, which speed up execution and reduce manual errors when experienced, accountable professionals run the work.
The seven questions below help you compare loan administration services on that foundation, then test whether a provider can deliver it for your portfolio, operating model, and budget.
You can rely on a loan administrator when your team can verify its outputs from the records behind them, without recreating the calculations. If verification means rebuilding, you have a second workload, not an outsourced one.
Take an interest notice. The figure is one part of the service. Seeing the principal balance, rate, accrual period, day-count convention, and adjustments that produced it is what makes the figure verifiable.
Without that access, your team builds its own calculation, compares results, and emails the administrator about differences. Repeated across a portfolio, this becomes a substantial parallel operation.
This is shadow booking: maintaining a parallel set of loan records to validate the administrator. It typically means re-running interest, fee, and PIK accruals, checking waterfalls and payment allocations, reconciling positions against internal records and the bank, and rebuilding investor reports from exports.
Some firms keep independent records deliberately, as part of their control framework. The real question is how much duplication exists only because the administrator's work is hard to inspect or trust.
During due diligence, ask the provider to show:
Your team should be able to answer routine questions on its own: current positions, how a calculation was produced, whether a payment was applied, and what is waiting for approval.
A portal of monthly reports is not the same as access to the underlying records used to administer your loans. Establish which one you are getting.
24/7 access is also not the same as real-time data. A portal can be always available and still show yesterday's balances. Ask:
For example, if an interest amount changes after an amendment, you should be able to follow it from the approved terms to the revised calculation. The record should show what changed, when it took effect, and who approved it.
Data ownership needs a practical meaning. Confirm your rights to source documents, loan records, and service outputs, and your ability to export them in usable formats. Ask how you can connect the data to your own systems, analytics, and AI tools, and what happens if you change providers.
The best setup is a single authoritative loan record that both the administrator's team and yours work from. Every handoff between systems is a chance for versions to diverge.
Ask where the authoritative loan record lives. Then follow information through a calculation, a notice, a payment, and a report. Identify where it is re-entered, copied into spreadsheets, or moved between systems, and how each handoff is checked.
When every workflow runs on the same structured records, there are fewer opportunities for drift. It also becomes easier to trace an output and understand the effect of a change.
That is why a technology demo belongs in the selection process, even when you are buying a managed service. Look for:
Whether the platform is proprietary or third-party matters less than how well the administrator uses it. Assess the system together with the people, controls, and procedures around it.
The practical test: does the technology give both teams the same view of the work while removing avoidable manual steps?
AI and automation improve loan administration when they run on reliable data and connected workflows, and when accountable people review the outcomes. They make work faster and reduce manual errors; they do not replace responsibility.
The mechanisms matter:
Ask the provider to walk through a real workflow and identify which steps are automated, which use AI, and which require human judgment. A claim that a service is "AI-powered" says little about how your loans will be administered.
Controls should be visible throughout. Reviewers need the source evidence, proposed changes, and relevant calculations. Permissions should define what the system may do, and approval requirements should match the consequences of the action. Clear human responsibility is also central to NIST's guidance on human oversight of AI.
Then test it. Introduce an incomplete instruction or an ambiguous term, and see whether the workflow flags it and who takes ownership of resolving it.
Judge results by processing times, correction rates, and exception handling the provider can substantiate. AI can support speed and accuracy; its presence alone proves neither.
An administrator is only as good as its handling of your most complex deals. Trust has to hold when the work gets complicated.
Test the provider with real examples from your portfolio:
Ask how each term is represented in the system and how the servicing team handles changes.
For example, take a pricing adjustment that becomes effective mid-accrual period. The administrator should explain how the effective date is set, how the calculation is updated, and how affected notices or reports are reviewed and reissued.
Some situations need specialist judgment. Establish who interprets unclear instructions, when the matter returns to your team or counsel, and how the decision is documented.
Evaluate the people as closely as the software. Relevant experience, backup coverage, and references from clients with comparable structures show whether the model works beyond a clean demo.
A strong operating model should translate into written turnaround commitments, with clear start points and owners.
Agree on turnaround for onboarding, facility booking, notices, amendments, payment activity, reconciliation, and reporting. Define when each clock starts, what inputs and approvals are required, and how cutoff times affect delivery.
"Next business day" only means something when both sides know whether the clock starts at receipt, after clarification, or after approval.
Measure responsiveness separately. Your team should answer many basic questions directly from the shared records. Questions that need investigation should have a named owner and a resolution target.
Ask how overdue work and unresolved discrepancies are surfaced. You should be able to tell what is waiting on your approval versus what is waiting on the administrator, and why anything is delayed.
Speed only matters if the work stays accurate, reviewable, and visible throughout.
The true cost of a loan administrator is its fee plus the internal work your team still carries. Define the service boundary before you compare prices.
Loan administration can include onboarding, interest and fee calculations, notices, payment tracking, amendments, reconciliation, covenant tracking, and reporting. The exact scope depends on the engagement, so be precise:
Review integrations with the same care. A direct system connection, a scheduled file transfer, and a spreadsheet your team uploads each create a different workload. Establish what data moves, how often, and who fixes failures.
Onboarding needs a defined plan for historical data, opening balances, missing documents, and acceptance checks. Any parallel run should have an agreed purpose and a clear end point.
Then compare total cost: the administrator's fee, charges for additional activities, and the internal effort to keep everything running. Ask shortlisted providers to price the same representative portfolio and expected activity.
The best measure of value is how much reliable execution you get, and how much checking, chasing, and reconstruction your team no longer has to do.
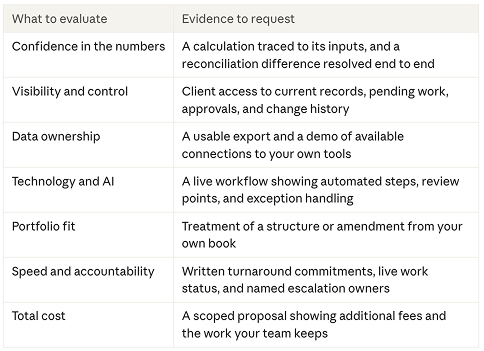
The most reliable way to compare loan administrators is to run one representative, anonymized loan through each shortlisted provider. Follow it from setup through an amendment, a payment discrepancy, and reporting, using the same access your team would actually receive.
Use this scorecard to record what each provider demonstrates:
Outsource the work, not the visibility. Hypercore provides AI-native loan administration services for private credit. Our loan operations team runs your book and is accountable for delivery, while AI agents execute and help verify workflows underneath.
One shared record. Our team works on the same platform and loan records you see: positions, calculations, servicing status, pending approvals, and full change history. Every number traces to its inputs, so verifying our work never means rebuilding it.
Your data stays yours. Beyond direct access and exports, clients can use Hypercore's MCP to build their own views, analysis, and AI agents on top of their loan book.
Built for complex structures. PIK, delayed draws, revolvers, multi-tranche and co-lending structures, and retroactive amendments are modeled natively on our purpose-built loan management platform, with history preserved.
Defined turnaround. T+1 facility booking, next-business-day waterfall execution after approval, and daily bank reconciliation.*
Start with one deal. Apply the test above to Hypercore. Bring us a representative loan and follow it from setup through an amendment, a payment discrepancy, and reporting.
*Turnaround commitments apply once required documents, inputs, and approvals are received, within the agreed service scope.
Replace rebuilding with verification. When the administrator works on the same loan records your team sees, and every accrual, allocation, and balance traces to its inputs, your team checks exceptions instead of re-running the whole book. Keep independent records only where your control framework deliberately requires them.
It should apply the amended terms from the correct effective date, recalculate every affected accrual, and show the difference against what was previously calculated. Affected notices and reports should be corrected and reissued, and the record should show the prior terms, the new terms, who prepared the change, and who approved it.
Yes. The administrative agent is a named role in the credit agreement with legal duties to the lending group. Many funds or lead lenders keep that role and outsource the operational work behind it, such as booking, calculations, notices, payments, and reconciliation, to a loan administrator.
It should mean your team sees the same current records the administrator works on: positions, calculations, pending approvals, and change history, with clear timestamps. A 24/7 portal that publishes periodic reports is not real-time visibility. Ask which data updates continuously and which depends on external feeds.
Give AI access through a controlled layer, not raw exports. Permissions should define what an agent can read or propose, consequential actions should require human approval, and every action should leave an audit trail. Funds should also be able to build their own agents and analysis on their loan book, not just consume the administrator's reports.
A turnaround commitment for each activity, such as facility booking, notices, waterfall execution, and reconciliation. It should also define when each clock starts, the inputs and approvals required, cutoff times, and how delays and open discrepancies are reported. A commitment without a defined start point is hard to hold anyone to.
Yes, and it is often the lowest-risk way to evaluate a provider. Starting with a single deal tests the data migration, calculations, exception handling, and reporting on a real loan, without displacing existing relationships. It also gives both sides clear evidence before a broader transition.